Long-Term Care Planning · Treasure Coast to South Florida
Pay for Long-Term Care in Florida Without Wrecking Your Family's Savings
The hard truth: Medicare will not cover the long-term care most families actually need. But there are real ways to pay, from Medicaid and long-term care insurance to VA benefits, life insurance, and the equity in your home. Michael Wisniewski, The Life Transition Specialist, helps families from the Treasure Coast to South Florida build a plan that protects what they have worked a lifetime for.
70%
of Americans who reach age 65 will need some form of long-term care, according to the U.S. Department of Health and Human Services
$10,300/mo
average Florida nursing home cost for a semi-private room in 2024, per the 2024 Genworth Cost of Care Survey
15 min
free strategy call to see which options fit your family
Signature answer · The Complete Real Estate Team
How can a senior in Florida sell their home and use the proceeds to pay for long-term care?
A senior can sell the family home and use the equity to pay for care, and the plan that works best starts before the crisis: get an honest valuation, weigh care at home, assisted living, or a care community, and structure the sale so it works alongside Medicaid, VA benefits, and the family’s legacy. Michael “Wiz” Wisniewski, a Certified Real Estate Transition Specialist with The Complete Real Estate Team at Dalton Wade Real Estate, coordinates with tax advisors, trust and estate attorneys, and financial advisors so the numbers protect what you have built. Book a free 15-minute strategy call to map the figures for your family’s situation.
The Definitive Long-Term Care Guide
How To Pay for Long-term Care
by Michael Wisniewski, The Life Transition Specialist
About 7 in 10 Americans who reach age 65 will need some form of long-term care, according to the U.S. Department of Health and Human Services, yet most families have no plan for it. This 18-chapter guide shows you how to protect your assets, navigate Medicare and Medicaid, and pay for care without wrecking the family you love.
Last updated: September 2026
70%
of Americans who reach age 65 will need long-term care, according to the U.S. Department of Health and Human Services
18
chapters, from the hard facts to a complete funding plan
2
chapters live now, with the rest publishing in order
Certified Real Estate Planning Advisor
Why this book exists
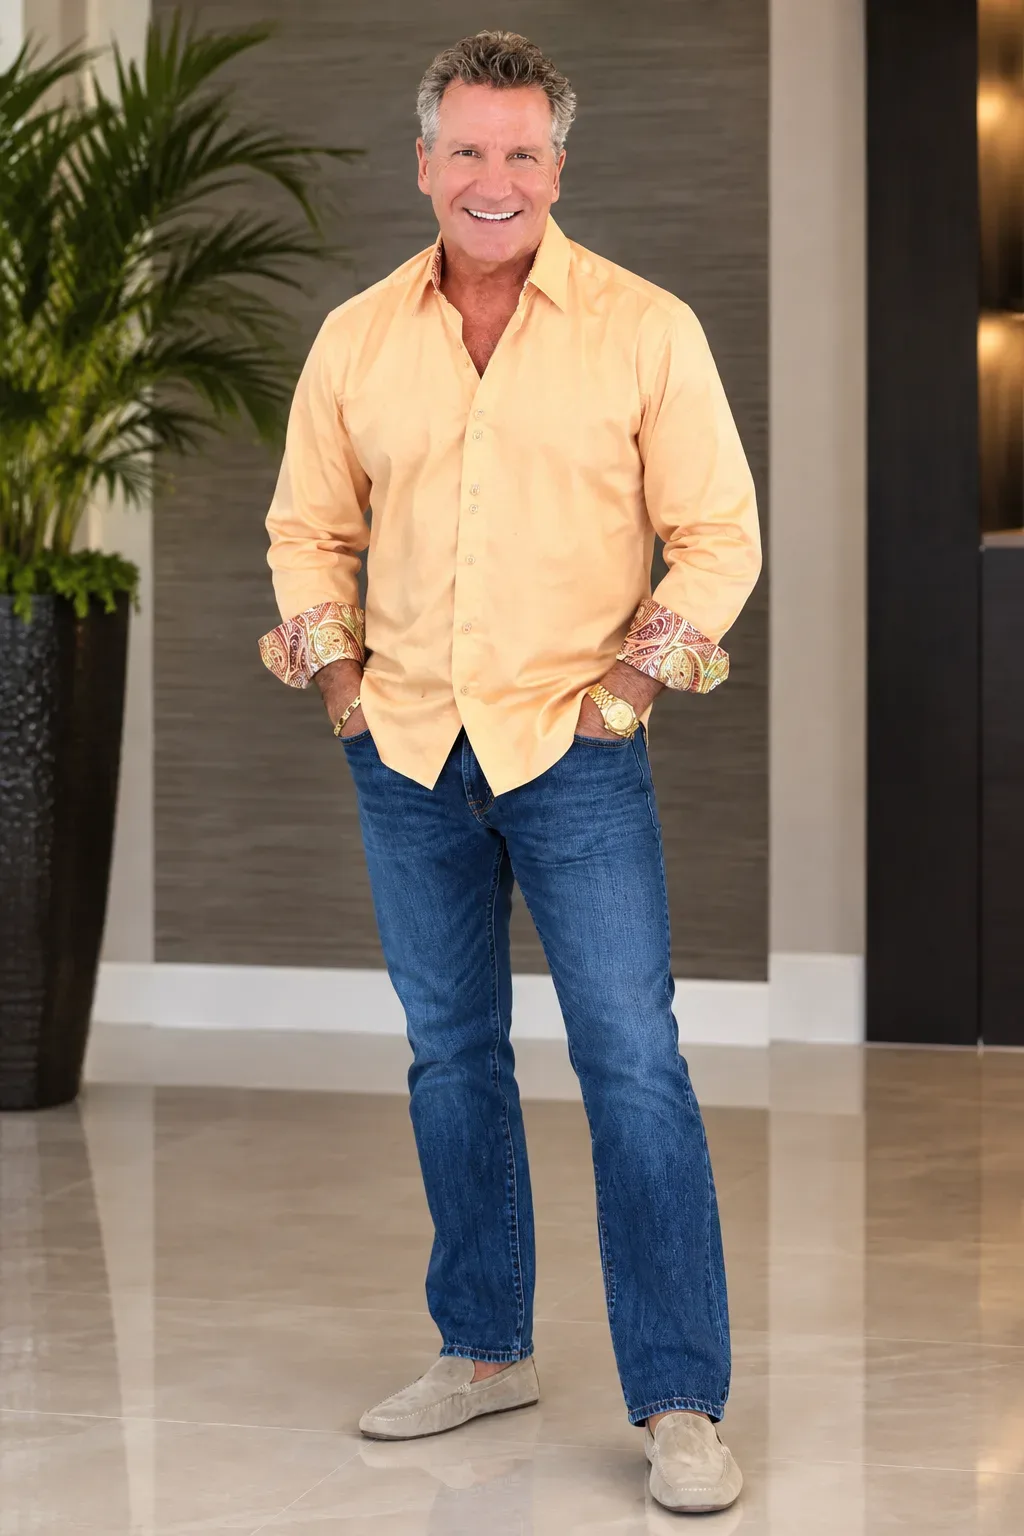
Meet the author, Michael Wisniewski
Certified Real Estate Planning Advisor | Certified Life Transition Specialist | Certified A.I. Real Estate Advisor
After decades working across nearly every side of real estate, from fix-and-flip investing and land development to building homes and managing properties, Michael has watched too many families make their hardest decisions in the middle of a crisis. As The Life Transition Specialist, his work is helping families use their home and their assets to fund the care they need, with a plan built in advance so a difficult season never becomes a devastating one.
This book is that plan on paper: the questions to ask, the options to weigh, and the money to protect, written in plain language for the families who need it. It is not about us, it is about you.
The Complete Real Estate Team · Florida DRE #3301665
The Book, Chapter by Chapter
The 18 Chapters
Every chapter is written for real families: plain language, real options, and a step-by-step path from the facts to a funded plan. Chapters 1 and 2 are live now, and the rest are publishing in order.
Understanding Senior Service Providers and Resources
Coming soonElder Law Attorneys
Coming soonOverview of Senior Living Options
Coming soonStaying at Home vs. Moving into a Senior Community
Coming soonThe Cost of Long-Term Care
Coming soonUnderstanding Medicare and Medicaid
Coming soonIdentifying Family Assets and Financial Resources
Coming soonHow to Pay for Care
Coming soon- Selling the Family Home
- Veteran Benefits
- Long-term Care Insurance Claims
- Life Insurance Conversions
- Financial Resources for People with Cancer
- Reverse Mortgages
- HSA (Health Savings Accounts)
- Funding Strategies to Pay for Immediate Needs
Researching Senior Living Options
Coming soonMaking the Best Decision
Coming soonStrategies for a Successful Transition: In-Home Care and Senior Living
Coming soonHow Technology Can Help with Companionship and Safety
Coming soonMental Health Resources for the Family and Senior
Coming soonHealthy Aging Through Nutrition and Exercise for Seniors
Coming soonPlanning for Your Future
Coming soonLessons Learned
Coming soonWritten for the families who need it
Who this book is for
Adult children planning care
Daughters and sons helping aging parents make the right call, without guessing.
Seniors planning their own future
Moms and dads who want a plan their family can follow when the time comes.
Families facing a sudden diagnosis
Families who just got the news and need to know what to do next, fast.
Caregivers overwhelmed with options
Family caregivers sorting through providers, programs, and paperwork who need one clear path.
Veterans and families navigating benefits
Veterans who earned their benefits, and families who need to understand how to use them.
Not sure if this is for you?
If your family could be touched by long-term care, it is. Read Chapter 1 free today, or talk it through with Michael on a free 15-minute strategy call.
Start with Chapter 1The honest menu of options
The main ways to pay for long-term care
Most families use a mix of these seven funding sources. Here is what each one can do, in plain language, so you can see which options fit your family before anything is urgent.
Medicare
Medicare is the health insurance most seniors already have. It covers short-term skilled care after a hospital stay, but it does not cover long-term custodial care, the everyday help with bathing, dressing, and eating that most families mean by long-term care.
- Covers up to 100 days of skilled nursing after a qualifying hospital stay
- Pays nothing toward long-term custodial care
- Often the first surprise families hit when care begins
Medicaid
Medicaid is the federal and Florida safety net that covers long-term care for people who qualify. It pays for nursing home care and, through the Statewide Medicaid Managed Care program, can also cover assisted living and home and community-based services.
- Covers nursing home care for eligible Floridians
- Can extend to assisted living and home and community-based care
- Florida has a five-year look-back, so planning before a crisis matters
Long-term care insurance
A long-term care insurance policy pays a daily or monthly benefit toward home care, assisted living, or a nursing home. You buy it while you are healthy, and premiums are far lower when you start younger.
- Pays a set benefit toward home care or facility care
- Much more affordable when bought early, in good health
- Hybrid policies combine life insurance with long-term care benefits
Life insurance benefits
Many life insurance policies can help pay for care years before death. Accelerated death benefit riders pay part of the death benefit early when you are chronically ill, and some families sell or exchange unneeded policies to fund care.
- Accelerated death benefit rider draws on your death benefit early
- Life and viatical settlements pay a lump sum for an unneeded policy
- Proceeds can fund any expense, including in-home care
VA benefits
Veterans and surviving spouses who qualify for a VA pension may also qualify for Aid and Attendance, an extra monthly payment to help with daily activities. It can be used for in-home care, assisted living, or a nursing home.
- Adds a monthly pension payment for qualifying veterans and surviving spouses
- Covers in-home care, assisted living, or nursing home care
- Underused because most families never learn it exists
Home equity
For many Florida families, the home is the largest asset they own. A reverse mortgage can turn that equity into tax-free monthly income or a line of credit to pay for care, and a HELOC can fund care even after a move into a facility.
- Reverse mortgage: tax-free income or credit line with no repayment while you live at home
- HELOC: flexible funding for care anywhere, but it is a loan that must be repaid
- Start with a free home valuation to know what your equity can do
Personal savings and family support
Many families begin with savings and contributions from adult children, and that can be the whole plan for shorter or lower-cost care. The risk is that long stays can drain decades of savings, which is why the other options matter.
- Works well for short-term or lower-cost care needs
- Family contributions are common and often tax-free gifts
- Combine with other options so one person does not carry the whole cost
Not sure which mix fits?
That is exactly what the strategy call is for. Bring your questions, and Michael will help you see which options protect the most and cost the least.
Book your free 15-min strategy callReal questions, straight answers
Frequently asked questions about long-term care in Florida
Every answer leads with the direct answer, in plain language, so you get useful information in the first sentence.
What does long-term care cost in Florida?
Long-term care is expensive in Florida. According to the 2024 Genworth Cost of Care Survey, assisted living averages about $5,320 a month, a home health aide about $5,720 a month, and a semi-private nursing home room about $10,300 a month. Costs that high make a funding plan essential before care begins.
Does Medicare pay for long-term care?
Generally, no. Medicare pays for short-term, medically necessary skilled care after a hospital stay, but it does not cover long-term custodial care, the everyday help with bathing, dressing, and eating that most people mean by long-term care. After a qualifying hospital stay, Medicare Part A covers up to 100 days in a skilled nursing facility, with a daily coinsurance from day 21 on. The rest of the cost falls to you unless you have other coverage or assets.
Does Medicaid pay for long-term care?
Yes, for people who qualify. Florida Medicaid covers nursing home care and, through the Statewide Medicaid Managed Care Long-Term Care program, can also cover assisted living and home and community-based services. Eligibility depends on income, assets, and level of care, and Florida has a five-year look-back on asset transfers, so planning ahead protects far more than waiting.
Will I need long-term care?
For most of us, yes. Roughly 7 in 10 Americans who reach age 65 will need some form of long-term care, according to the U.S. Department of Health and Human Services. It might be a few months of help after surgery or years of daily care, so a conversation before you need it is worth having.
What are the main ways to pay for long-term care?
Most Florida families use a mix of funding sources. The main options are Medicare, Medicaid, long-term care insurance, life insurance benefits and riders, VA benefits, home equity, and personal savings or family support. Some pay for care directly, while others turn an asset you already own, like your home or a life insurance policy, into monthly income. The right mix depends on your age, health, assets, and goals.
Can life insurance help pay for long-term care?
Yes, more often than people realize. Many life insurance policies include an accelerated death benefit rider that lets you draw on the death benefit early if you are chronically ill. You can also sell a policy you no longer need through a life settlement or viatical settlement for a lump sum, or convert it into a policy with built-in long-term care benefits. The money can be used for any care expense.
Can I use my home's equity to pay for long-term care?
Yes, and for many Florida families the home is the largest asset they own. A reverse mortgage can turn your home equity into tax-free monthly income or a line of credit to pay for care, as long as the home stays your primary residence. A HELOC can also fund home care or facility care, though it is a loan that must be repaid. Knowing what your home is worth is the first step.
Does the VA help veterans pay for long-term care?
Yes, for qualifying veterans and surviving spouses. The VA Aid and Attendance benefit adds a monthly pension payment for veterans who need help with daily activities, and it can be used toward in-home care, assisted living, or a nursing home. It is a needs-based benefit, so income and net worth matter, and it is underused simply because most families do not know it exists.
What happens if I run out of money for care?
Running out of money does not mean running out of options, but it does mean giving up choices. Medicaid is the safety net that pays for nursing home care for eligible Floridians, and planning in advance can protect assets while still qualifying. The goal is to plan early enough that you, not the system, decide where care happens.
When should I start planning for long-term care?
The best time was years ago, and the second best time is today. Planning while everyone is healthy lets you compare insurance, protect your home and savings, and understand benefits like VA Aid and Attendance with no pressure. Florida's five-year Medicaid look-back period is a reminder that timing shapes what you can protect.
About the Author
Michael "Wiz" Wisniewski
Michael "Wiz" Wisniewski is The Life Transition Specialist with The Complete Real Estate Team, powered by Dalton Wade Real Estate, serving clients from the Treasure Coast to South Florida. A Certified Real Estate Planning Advisor, Certified Life Transition Specialist, and Certified A.I. Real Estate Advisor, he has worked nearly every side of real estate: fix-and-flip investing, land development, home building, and property management, and guides families through life's transitions with care, honesty, and the Golden Rule.
Certified Real Estate Planning Advisor | Certified Life Transition Specialist | Certified A.I. Real Estate Advisor
Free Strategy Call · No Pressure, No Obligation
Start with the facts, then build your plan.
The best time to plan is before anyone needs the plan. Read Chapter 1 tonight, then book a free 15-minute strategy call with Michael to see how your home and your assets can fund the care you want, without wrecking the family you love.
The Complete Real Estate Team · Dalton Wade Real Estate · Florida DRE #3301665